Budhigandaki hydropower faces another plan change as authority returns
The 1,200MW reservoir project, a national pride project since 2012/13, has an approved financing plan. The government now wants a new authority to build it.
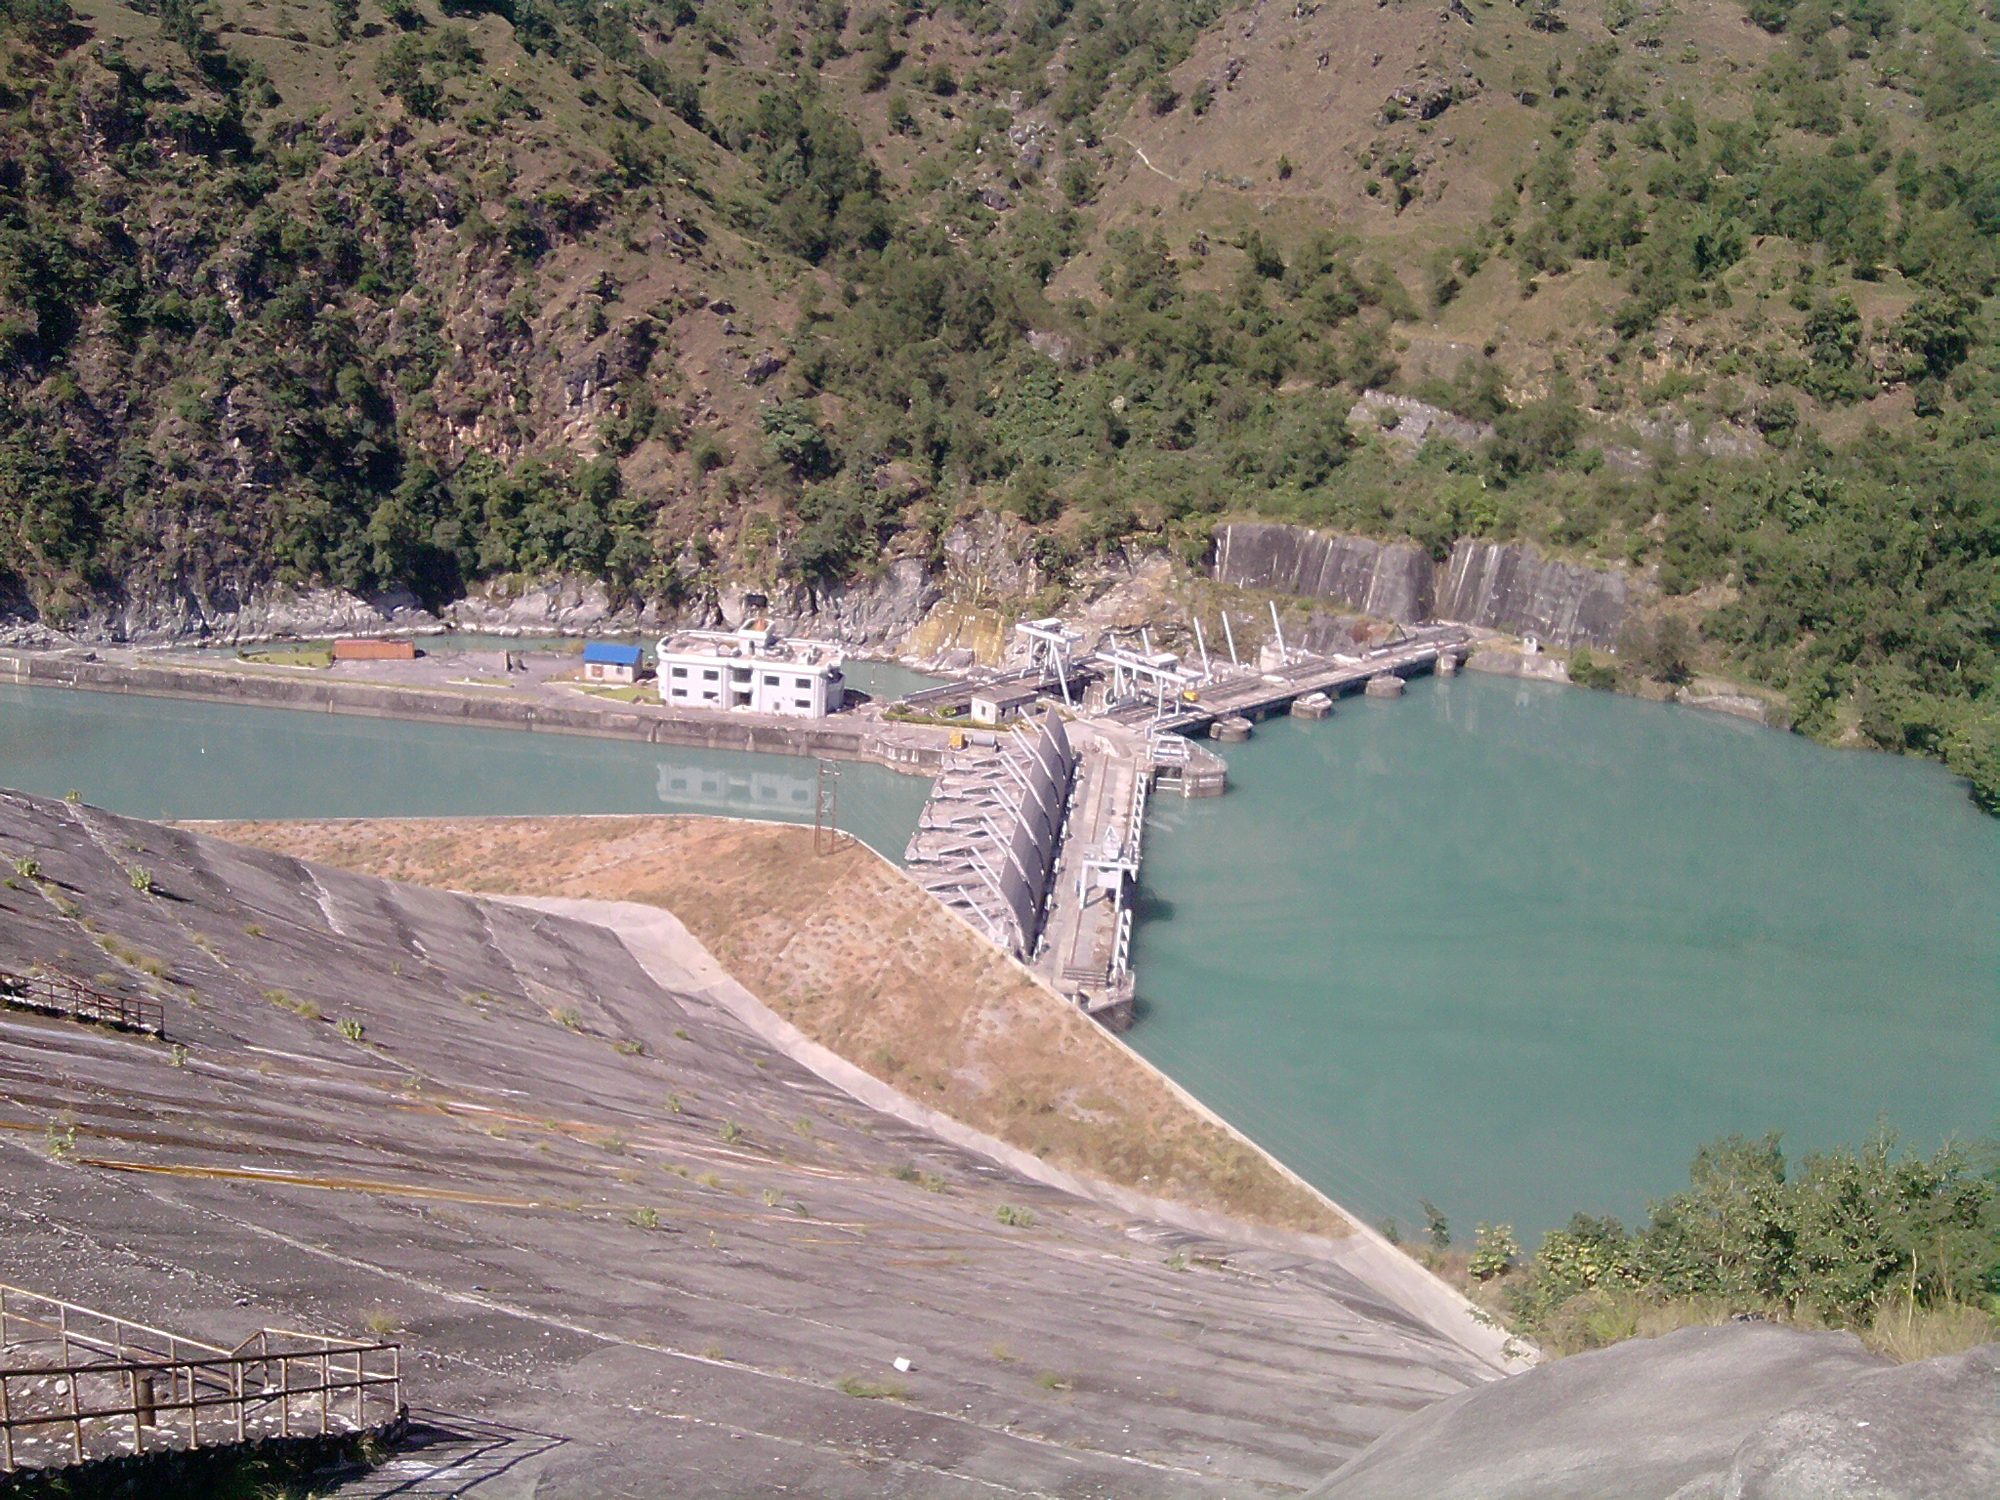
Few projects in Nepal carry as much official ambition as Budhigandaki. The 1,200-megawatt reservoir scheme on the border of Dhading and Gorkha districts was told on 23 March 2026 to proceed under an approved financing plan. On 16 October 2026 the Cabinet moved to give it a new institution.
The question for investors and lenders is whether a new authority speeds up a project Nepal needs for winter power, or restarts a clock that has run for well over a decade. The project was meant to be finished in 2026/27.
The scheme became a national pride project in 2012/13. The Office of the Auditor General's 60th annual report puts its initial estimated cost at Rs260bn.
The budget for 2025/26, from then finance minister Bishnu Paudel, proposed a public-private partnership. The interim government formed in September 2025 then approved a financial structure. After Cabinet decisions on 16 January 2026 and 24 February 2026, the Energy Ministry told the promoter, Budhigandaki Jalbidyut Company Limited, to proceed on 23 March 2026.
The first budget of Prime Minister Balendra Shah's government, presented on 29 May 2026, changed course. Finance Minister Swarnim Wagle announced that an empowered authority would build the project. On 16 October 2026 the Cabinet gave in-principle approval to draft the Budhigandaki Development Authority Bill.
- Designated a national pride project
- Ministry tells promoter to proceed under approved financing model
- Budget announces development through an authority
- Cabinet approves drafting the authority bill
Source: The Kathmandu Post
The base cost is $2.77bn, around Rs374bn. With Rs32bn of interest during construction, the total reaches Rs406bn.
The approved model is 70% debt and 30% equity. The promoter company is owned 80% by the government and 20% by the Nepal Electricity Authority. The government's commitment would total Rs248bn, made up of Rs97.47bn in equity and Rs150bn in concessional loans. The Rs46bn it has already spent, including on compensation, has been converted into equity in the company. The plan says the government must still secure a further Rs228bn. The electricity authority would add Rs24.37bn in equity.
The rest is meant to come from a share issue by the electricity authority, energy bonds, bank loans, infrastructure tax revenue, and investment from Nepalis abroad and the public.
Source: The Kathmandu Post
The plan leans on domestic institutional capital. The government would facilitate Rs30bn of energy bonds eligible for the statutory liquidity ratio (SLR), the portion of deposits banks must hold in approved assets. Banks, insurers and public funds could buy them. A further Rs104bn of debt would come from a consortium of the Employees Provident Fund, Citizen Investment Trust, Social Security Fund, the Hydroelectricity Investment and Development Company (HIDCL), Nepal Telecom and commercial banks.
That makes the delivery model a matter for Nepal's financial system, not only for engineers.
Former energy secretary Anup Upadhyay argued after the budget that an authority was the wrong vehicle. He proposed counting state spending to date as equity and inviting investment for the balance. After the Cabinet decision he mocked the idea, likening it to a remedy applied to the wrong part of the body.
The company's chief executive, Arun Rajauria, offers reassurance. He said the company has begun drafting the bill, which will go to the Ministry of Law, Justice and Parliamentary Affairs for consultation. Contracts and construction under way would not stop, he said, and the company's responsibilities would pass to the authority once it exists. The bill is meant to allow for longer-term plans in integrated land development, infrastructure and urban development.
Both views may be partly right. A wider mandate for land and urban development is a different ambition from building a dam, and it may justify a separate legal body. But the sources describe no timetable for the bill, and the 2026/27 target is close.
The risk for lenders may lie less in the authority itself than in the interval before it exists. Until the bill is drafted, reviewed and passed, financiers may ask which entity is the counterparty. The plan to float shares to the public near or after completion also depends on a shareholding structure that an authority could alter.
Watch for the text of the bill, and whether it keeps the 70:30 financing model and existing contracts intact. Watch too whether the law ministry clears the draft, how the government plans to secure the further Rs228bn, and whether the 2026/27 completion target is formally revised.
How this story was made: researched and written by The Standard’s desk with AI assistance, from the published reporting and official data credited below, and checked against those sources. Our standards.
The long view Nepal's hydropower, from load-shedding to exports