Nepal's startups grow up under a thicket of new rules
A change at the top of eSewa, fare caps for ride-hailing apps and a troubled state loan scheme show how the state is catching up with the digital economy.
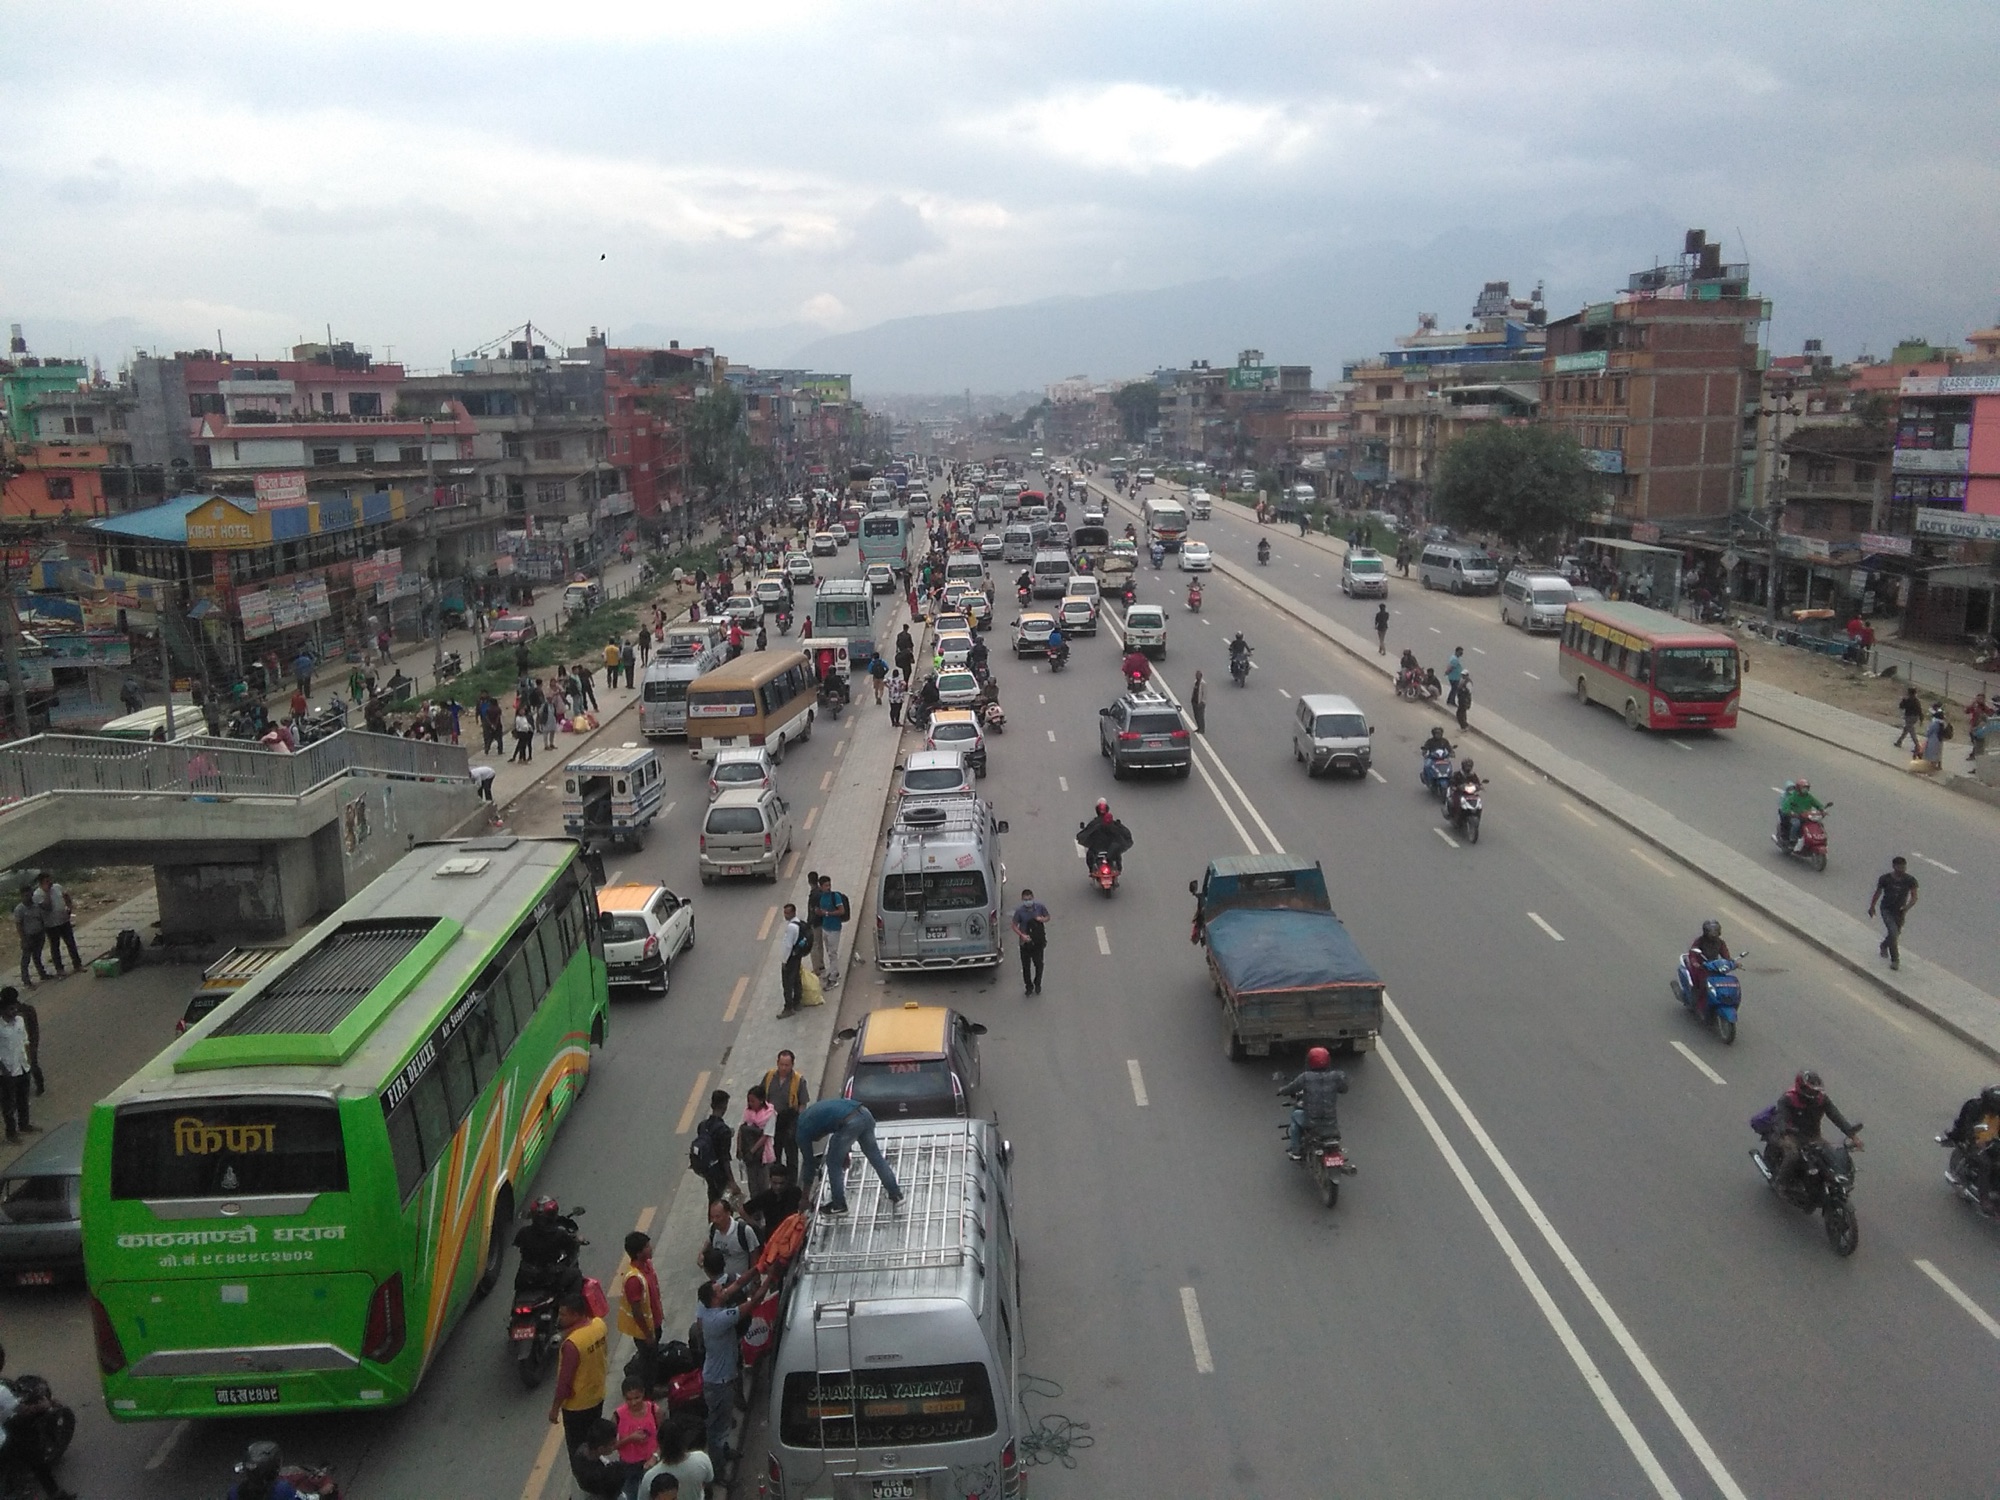
For most of the past decade, Nepal's best-known technology companies grew in a regulatory grey zone. Payment wallets ran ahead of banking rules, ride-hailing apps operated for years before the law recognised them, and the state's support for startups amounted to promises in budget speeches. That is changing. The changes are not all welcome, but they suggest the sector has become too large to ignore.
A new face at eSewa
The clearest sign of maturity is at eSewa, the country's largest digital wallet. Its parent, F1Soft, has appointed Niraj Sharma as chief executive, succeeding Jagdish Khadka at the end of his four-year term. Sharma spent about 18 of his 25 years in banking and payments at Nabil Bank. Choosing a career banker to run a fintech firm says something about where the business is heading.
In an interview with the Kathmandu Post on 28 September, Sharma named three problems: intense competition, low financial literacy and rising cyber fraud. He described wallets and banks as complementary rather than rivals, and said service quality, from uptime to whether transactions go through, could not be compromised. eSewa has been preparing an initial public offering; Sharma said he was too new in the job to give details of its progress. A listing would let ordinary investors buy into a home-grown technology company. For context on the market it would join, see our report on the capital market's 21-point plan.
Ride-hailing gets a rulebook
The bigger change has come for ride-hailing. In April the Department of Transport Management finalised the Digital Mobility Service Operation Standard 2026, the first national framework for apps such as Pathao, inDrive and Yango. It caps fares at Rs 25 a kilometre for motorbikes and Rs 55 for cars, limits surge pricing to 30% and 40% respectively, and caps platform commission at 10% of a driver's earnings.
Vehicles must be registered as digital mobility services and be no older than 15 years. Drivers need a licence held for at least a year and must join the Social Security Fund. Cars must carry GPS trackers and dashboard cameras, and every app must include an SOS link to the police. A traffic accident fund, paying up to Rs 1m for serious accidents, will be financed by a 1% deduction from fares and 0.5% of platform revenue.
Tax followed. Since 17 July, under the Finance Act for 2026/27, ride-hailing platforms must collect 5% VAT from drivers on each trip, issue invoices on their behalf and pay the money to the Inland Revenue Department by the 25th of the following month. The platforms still charge the standard 13% VAT on their own commissions and booking fees. Yeshu Thakali, managing director of Pathao Nepal, backed the 5% rate when it was proposed in June, calling it a balanced measure that formally recognises the industry without loading heavier costs on to riders. It also ended a long argument over whether the full 13% should apply to entire fares.
The loan scheme that did not work
The state's direct support for new firms has a weaker record. A subsidised loan programme, first announced in 2018 but only operating from 2023, has lent about Rs 1.88bn to nearly 1,500 startups at 3% interest through Rastriya Banijya Bank, according to the Kathmandu Post. Of Rs 770m disbursed in the past two years, only Rs 28.2m has been repaid. Entrepreneurs told the paper that many recipients were ordinary restaurants and clothing shops rather than innovative businesses, that loans of up to Rs 2m were too small to matter, and that most of the firms closed within a year.
Demand has not fallen. This year 10,244 applications produced 1,301 preliminary selections, with about 750 businesses expected to receive money. The finance minister, Swarnim Wagle, has meanwhile announced a Nepal Enterprise Facility with Rs 500m to bring startups and small firms into a more structured system of finance and policy support.
What it adds up to
The pattern is a state moving from neglect to supervision. Price caps and commission limits will squeeze ride-hailing margins, and the VAT regime adds paperwork. Yet formal recognition also gives the platforms legal certainty they lacked, and a wallet company preparing to list is a sign that investors expect these businesses to last. The lesson of the loan scheme is that the state is better at writing rules than picking winners.
How this story was made: researched and written by The Standard’s desk with AI assistance, from the published reporting and official data credited below, and checked against those sources. Our standards.